For Japan fans and language learners, this is also a useful window into business vocabulary, from 宿 (yado, inn) and 貸切露天風呂 (kashikiri rotenburo, private open-air bath) to occupancy and ADR. The numbers tell a very Japanese story, and it isn't a romantic one.
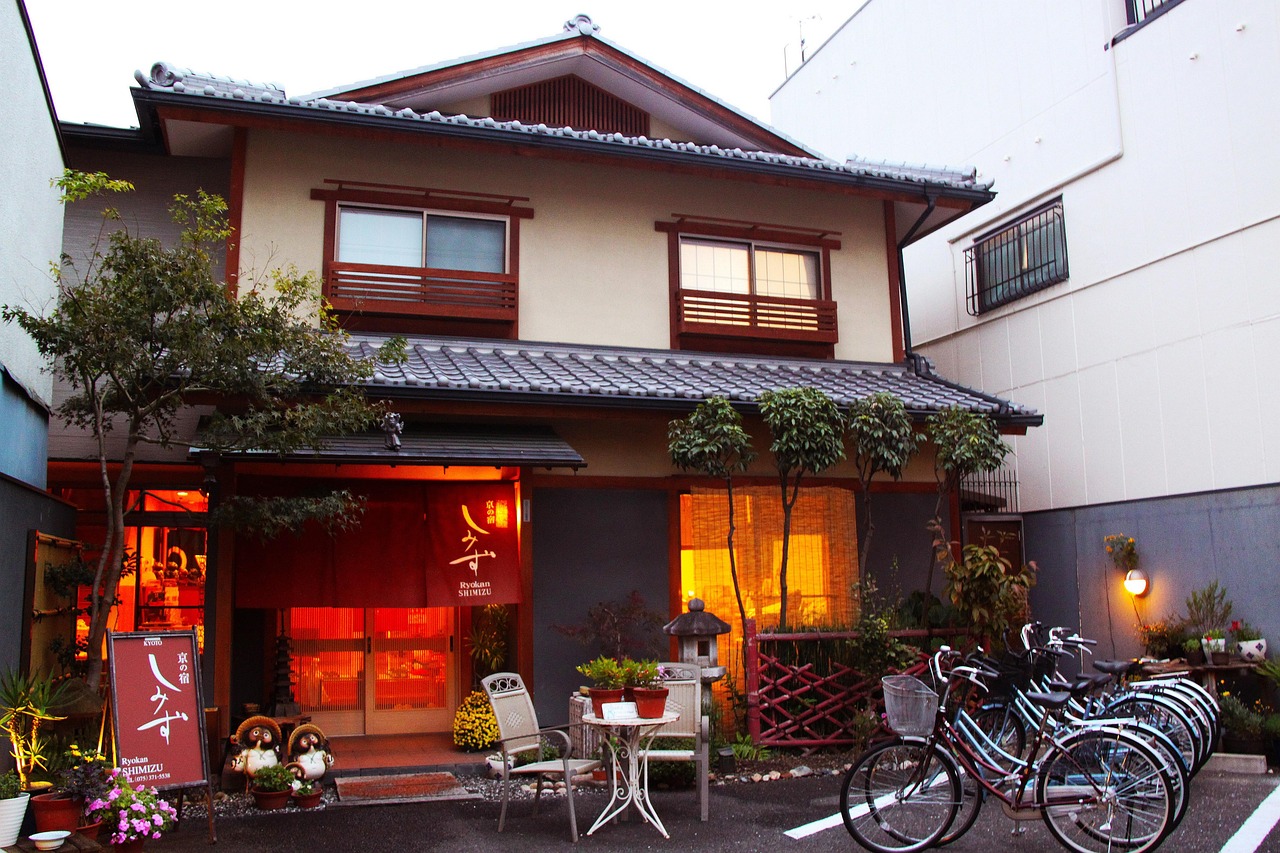
Picture this: a beautiful onsen ryokan with 畳 (tatami, tatami mat) rooms, a quiet river nearby, and a reputation built over decades. The lobby smells of 檜 (hinoki, Japanese cypress), the dinner's kaiseki, and guests come for the bath as much as the bed. But if the price model's wrong, even a place that feels timeless can start bleeding value fast.
The debate around ryokan pricing is really a business debate, not just a tourism one. Investors, operators, and local owners are looking at four places especially closely: Yuugawara, Izu-Nagaoka, Minakami, and Kusatsu. Each is an established hot spring area, each has name recognition, and each faces the same uncomfortable question: what is the property actually worth when you run the numbers instead of just admiring the view?
Why onsen ryokan valuations are being reset
Fun fact: a ryokan can look packed on weekends and still fail the profitability test. The reason's simple: occupancy, or OCC, only tells part of the story, while average daily rate, or ADR, shows whether guests are paying enough to cover staffing, maintenance, and debt. A property with 70 percent occupancy and weak room rates can still underperform a smaller ryokan with fewer rooms but stronger pricing power.
Take Yuugawara for instance. It has long been a classic escape for Tokyo visitors, with easy access and a loyal repeat base. Yet that convenience also creates a ceiling, because guests compare it with day-trip options, not just other ryokan. If ADR doesn't rise with labour and energy costs, the asset can look stable on the surface and fragile underneath.
That's where the recalculation starts. Older valuation habits often leaned on sentiment, land value, and the idea that an onsen address automatically protects earnings. Hand on heart: that logic feels increasingly shaky. Today, buyers are asking how much cash flow the property can really generate after salaries, utilities, renovation reserves, and booking-channel commissions. Convinced yet?
ADR and OCC: the two numbers that matter most
Trust me on this one: if you only remember two hotel metrics, make them ADR and OCC. ADR tells you what each occupied room earns on average, while OCC shows how many rooms are sold. Multiply them, add the room count, and you start to see whether a ryokan has real pricing strength or just seasonal popularity.
Did you know that...? In many ryokan cases, food and bath experiences complicate the picture even more, because room revenue is only one slice of total spending. A guest might book a half-board stay, enjoy local sake, and choose a private bath upgrade. That sounds lovely, and it is, but the operator still has to make the margins work across every service line. No wonder, because onsen towns are often dealing with aging buildings, limited staff, and rising costs at the same time.
Take Izu-Nagaoka for instance. It benefits from the broader Izu brand, good access from the Tokyo area, and a steady leisure market. Yet a property there can't rely on location alone. If occupancy is decent but ADR sits too low, the revenue line stays capped. If ADR climbs without enough occupancy, the fixed costs still hurt. The sweet spot is a balance, and that's what investors are now pricing, not just the postcard image. My tip: when you see a ryokan advertisement, try to think like an operator, not a tourist, and ask what the monthly cash flow probably looks like. Wild, isn't it?
Why 12 percent return is becoming the benchmark
Unlike what we're used to with sentimental buying, the new yardstick is return on capital, and 12 percent is increasingly used as a rough target. That doesn't mean every ryokan must instantly hit exactly 12 percent, but it does mean acquisitions are being judged against a clear business hurdle. If the expected return is lower, the price has to come down, or the renovation plan has to be stronger.
That reminds me: Minakami and Kusatsu are perfect examples of why this matters. Both are known onsen destinations with strong domestic recognition, yet their economics aren't interchangeable. Minakami can appeal to nature seekers and ski traffic, while Kusatsu has one of Japan's most famous hot spring brands and a powerful draw for first-time visitors. Still, fame doesn't pay the bills on its own. If the property needs major capex, or if labour costs are high, the valuation must reflect that risk.
Here's the catch: a 12 percent return benchmark pushes everyone to think in systems. A ryokan with a robust yen-for-yen upgrade plan, strong repeat demand, and room for ADR growth can justify a higher price. A tired building with low OCC outside peak seasons can't. This is why some buyers are now saying the old price tags are too high, even when the bathwater is excellent. Convinced yet?
What Japan learners can take from this pricing shift
For language learners, this whole debate is also a handy vocabulary lesson. Ryokan means traditional inn, onsen means hot spring, and kashikiri rotenburo refers to a private open-air bath. If you hear a local say 観光 (kanko), they mean tourism, while 経営 (keiei, management; business operations) means management or business operations. These words show up constantly in articles about regional travel and real estate, and they help you read Japanese news with much more confidence.
Insider tip: when you read Japanese reports on hospitality, watch for words like 利益 (rieki) for profit, 資産 (shisan) for assets, and raito for rate, often used in finance contexts. Japanese business writing loves concise shorthand, so ADR and OCC may appear side by side with terms like shun, off-season, and kaikaku when hotels try to reform operations. That makes the sector a surprisingly good study case for learners who want practical vocabulary instead of textbook examples.
My verdict: Japan's ryokan market isn't losing charm, it's being forced to price charm properly. Yuugawara, Izu-Nagaoka, Minakami, and Kusatsu all have strong identities, but identity alone won't settle the bill. If operators can lift ADR, manage OCC, and aim for a 12 percent return on capital, the next generation of ryokan can still thrive. But that's not all.
For more Japan context and travel-business news, see more Japan news on jpnerd.com.
Frequently Asked Questions
What is ADR in hotel business?
ADR means average daily rate, the average room price a property earns per sold room.
Why does occupancy alone not show profitability?
Because a hotel can be busy but still earn too little per room to cover costs and generate a solid return.
Why is 12 percent used as a benchmark?
It gives investors a clear target for judging whether a property is priced fairly against its cash flow and risk.